
On this page 11 sections
- Who Can Register as a Tax Agent: The Legal Conditions
- The Training and Exam Route
- Registration Steps on EmaraTax
- Registration Fee, Renewal and CPD
- Individual Tax Agent, Juridical Tax Agent or Tax Agency
- Duties, Penalties and Delisting
- How Clients Use the Public Register
- Worked Example: Timeline and Cost
- Checklist Before You Apply
- From Registration to First Clients
- What is not published
This guide sets out what the Federal Tax Authority (FTA) and the tax procedures legislation require before you can act as a registered tax agent in the UAE: eligibility, the exam route, fees, renewal, duties and the public register. Every figure comes from FTA pages and legislation read on 5 October 2026, and each one carries its source.
Who Can Register as a Tax Agent: The Legal Conditions
Practising as a tax agent without being listed is not allowed. Article 12 of Federal Decree-Law No. 28 of 2022 on Tax Procedures says no person may practise the profession unless they meet the registration conditions, are listed in the Register of Tax Agents and hold a licence from the competent local authority. The detailed conditions sit in Article 12 of Cabinet Decision No. 74 of 2023 (the executive regulation, FTA consolidated copy dated 1 April 2026). The education and experience test can be met in three ways:
| Route | Degree | Experience |
|---|---|---|
| 1 | Bachelor’s or master’s in tax, accounting or law, recognised in the UAE | At least 3 years within the last 5 years |
| 2 | Bachelor’s in any other field, plus a valid professional qualification from a recognised institution | At least 3 years within the last 5 years |
| 3 | Bachelor’s in any other field | At least 5 years within the last 8 years |
Source: Cabinet Decision No. 74 of 2023, Article 12(1)(c), consolidated copy dated 1 April 2026.
The same article adds these conditions for a natural person:
- good conduct, and no conviction for a crime or misdemeanour prejudicial to honour or honesty, even after rehabilitation;
- completion of any training the FTA specifies and a pass in any qualifying examination it specifies;
- the ability to communicate orally and in writing in Arabic or English;
- valid professional indemnity insurance, held directly or through an employer, appropriate to the size of the business;
- a licence from the competent authority, or employment with a licensed entity;
- not being a current member of the Tax Disputes Resolution Committee.
The FTA’s EmaraTax user manuals (version 1.2, 2024) add that you must be a UAE resident to apply as a natural person tax agent.
Two FTA pages are worded differently from the regulation, so plan for the stricter reading. The FTA page “What requirements should I meet” (last updated 9 September 2025) asks for a language proficiency document “for both Arabic and English” and a certificate of medical fitness, while the regulation says Arabic or English and the service card (last updated 19 August 2026) does not list a medical certificate. The service card asks for an IELTS or TOEFL certificate if you select English.
The Training and Exam Route
The FTA service card for tax agent registration (19 August 2026) lists a diploma certificate in VAT or corporate tax among the required documents, plus FTA Tax Agent Arabic exam results where the FTA asks for proof. The EmaraTax manual “Register Natural Person Tax Agent with Exam Schedule” (24 June 2024) describes the sequence: after you submit, the FTA schedules an appointment for the Arabic exam and/or the Qualification Standards Tests, you accept a slot or ask to reschedule, then upload your results for review. Applicants who have already passed both use the separate “without exam schedule” manual.
For UAE nationals, the FTA runs the UAE National Tax Agent Programme (page last updated 16 June 2026). It aims for 500 Emiratis to obtain tax diplomas over three years, offers a VAT diploma of 6 days and a corporate tax diploma of 11 days, and the government covers the diploma fees and the tax agent registration fee. FTA news of 18 April 2026 reported the first cohort of 50: 25 on the VAT diploma and 25 on the corporate tax diploma.
Registration Steps on EmaraTax
- Create an EmaraTax account (FTA services run through UAE Pass) and choose the “Tax Agent (Natural Person)” profile.
- Upload your degree, proof of experience, police clearance or good conduct certificate, language evidence, VAT or corporate tax diploma, Emirates ID and passport. Files must be PDF, DOC or DOCX, up to 15 MB each.
- Sit the Arabic exam and/or Qualification Standards Tests if the FTA schedules them, and upload the results.
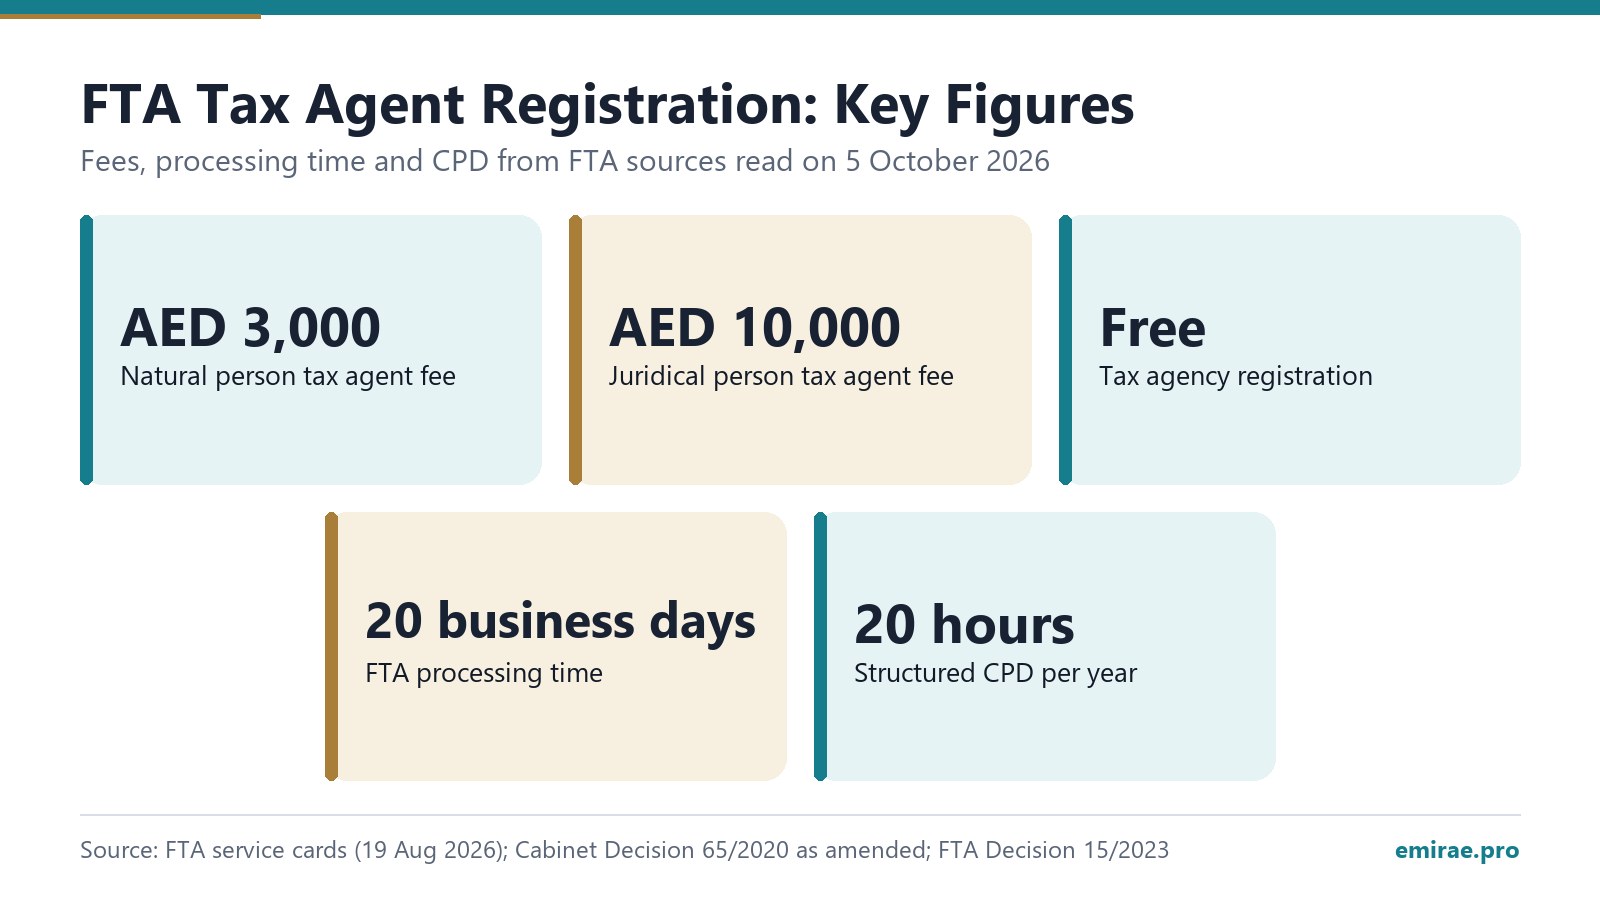
- Wait for the decision. The FTA service card gives 20 business days from a complete application; the regulation requires a decision or a request for more information within 15 business days (Article 13).
- Pay the fee within 20 business days of the approval notice, or the application is cancelled.
- The FTA lists you in the register within 5 business days of payment.
- Get appointed by a tax agency or a juridical person tax agent. The service card says this is what activates your status.
Registration Fee, Renewal and CPD
| Registration | FTA fee | Listing period |
|---|---|---|
| Natural person tax agent | AED 3,000 | 3 years |
| Juridical person tax agent | AED 10,000 | 1 year |
| Tax agency | Free | Not stated on the service card |
Sources: Cabinet Decision No. 65 of 2020 and its amendments, items 4 and 5 (FTA copy dated 24 December 2025); Cabinet Decision No. 74 of 2023, Article 13(8); FTA service cards for tax agent and tax agency registration (19 August 2026).
Renewal. The FTA sends an automated notice 60 days before your listing expires and a Renewal button appears on the dashboard (FTA renewal page, 22 July 2025). The regulation requires the renewal request no later than 20 business days before expiry; a later request is treated as a new application, and a listing that lapses is cancelled with all client links revoked (Article 13(8) to (10)). Renewal documents: a letter from your tax agency confirming employment, a police clearance or good conduct certificate, valid professional indemnity insurance and the renewal declaration form.
Continuing professional development. FTA Decision No. 15 of 2023 (in force since 1 January 2024) requires at least 20 hours of structured CPD a year for an agent listed for corporate tax or indirect taxes, and 30 hours for an agent listed for both, with at least 15 hours in each. Missed hours carry into the next year on top of that year’s requirement.
Individual Tax Agent, Juridical Tax Agent or Tax Agency
The FTA runs three separate registrations.
| Registration | Who | Key condition |
|---|---|---|
| Natural person tax agent | An individual | Article 12(1) conditions above; activated only once appointed by a firm |
| Juridical person tax agent | A firm licensed as an audit, tax or law firm | A supervising director or partner who meets the natural person conditions and works for no other firm; at least one registered natural person tax agent for every 10 employees working in tax (FTA Decision No. 14 of 2023) |
| Tax agency | A licensed legal person whose activities qualify | Trade licence, incorporation documents, owners’ IDs and professional indemnity insurance; at least one tax agent linked before it may practise. VAT registration is not required |
If you plan to run your own practice, the licence matters as much as the FTA step. Our guide on opening an accounting and bookkeeping firm in Dubai covers the licence and AML side, and opening an audit firm in the UAE covers Ministry registration for auditors.
Duties, Penalties and Delisting
Article 14 of Cabinet Decision No. 74 of 2023 sets the duties. A tax agent must:
- assist the client with its tax obligations under the agreement between them;
- keep client information confidential, unless the law requires disclosure;
- meet the CPD requirements;
- refuse any work or plan that may breach a law or harm the integrity of the tax system;
- keep information, documents and records for every client represented, and hand them to the FTA on request (Decree-Law No. 28 of 2022, Article 15).
Appointing an agent does not remove the client’s own responsibility (Article 14 of the Decree-Law). Under Cabinet Decision No. 40 of 2017, Table 1, item 13 (FTA consolidated copy, November 2025), a tax agent who fails to facilitate the FTA’s tax auditor faces a penalty of AED 20,000, payable from the agent’s own funds. The FTA must delist an agent who no longer meets the conditions, who threatens the integrity of the tax system, or who commits a serious violation or takes part in tax evasion (Article 13(13) of the regulation). The service card also states that registered agents are not FTA employees and must not present themselves as affiliated with the Authority.
How Clients Use the Public Register
The FTA publishes a searchable list of registered tax agents. On 5 October 2026 it showed 858 entries. Clients can filter by emirate or city and by previous experience, such as businesses subject to VAT, corporate tax, excise tax registration, non-resident businesses or SMEs, and each entry shows the agent’s TAAN number, firm, emirates served and contact details. The FTA’s own wording to taxpayers is to search for a registered tax agent in their area.
Your listing is proof a client can check in a minute, so quote your TAAN on proposals. But the register is a directory, not a ranking: your offer and specialisation still decide who gets hired.
Worked Example: Timeline and Cost
Our arithmetic, using the regulation’s maximum periods after a complete application and excluding the exam: 15 business days for the decision, 5 to receive the approval notice, up to 20 to pay and 5 to be listed gives at most 45 business days. If you pay on the day of approval, it is 25 business days. The FTA fee of AED 3,000 for three years works out at AED 1,000 a year. CPD for one area is 20 hours a year, or 60 hours over the three-year listing; for both areas it is 90 hours. On our platform a corporate tax lead costs AED 500, so the registration fee equals six corporate tax leads.
Checklist Before You Apply
- Degree certificate recognised in the UAE, and which of the three routes you meet.
- Experience letters covering the last 5 (or 8) years.
- Police clearance or good conduct certificate.
- IELTS or TOEFL if applying in English, or readiness for the Arabic exam.
- VAT or corporate tax diploma.
- Professional indemnity insurance, your own or your employer’s.
- A tax agency or juridical person tax agent ready to appoint you.
- A CPD log set up from day one.
From Registration to First Clients
A listing makes you eligible, not busy. Demand comes from companies that must register for and file corporate tax and VAT: an FTA press release of 26 September 2026 set 30 September 2026 as the deadline for filing returns and paying corporate tax for financial years ended 31 December 2025. On Emirae, clients post confirmed requests and firms reply with free offers, up to 20 in any 24 hours. You pay only when a client opens their contact details to you: AED 500 for a corporate tax lead, AED 500 for VAT and AED 800 for accounting, with no subscription (pricing, read on 5 October 2026). Up to three firms can unlock the same request. See how matching works on how it works, compare how others present themselves in VAT consultants in Dubai and accounting firms in Dubai, and read our lead generation guide for UAE service firms. Firms that list under corporate tax advisory receive the matching requests.
What is not published
- The exam fee, pass mark, format and number of attempts are not stated on the FTA pages and manuals we read.
- The FTA pages we read do not list accredited diploma providers for non-Emirati applicants.
- No minimum professional indemnity cover is set; the regulation says only that it must suit the size of the business. Ask your insurer and the FTA in writing.
- The time to schedule the exam is not published, so the 25 to 45 business day estimate above excludes it.
- FTA professional standards for tax agents issued in 2024 are referenced by law firms, but we could not open an official copy on tax.gov.ae on 5 October 2026, so we do not describe them here.
Frequently asked questions
What qualifications do I need to become a tax agent in the UAE?
Cabinet Decision No. 74 of 2023 requires a bachelor’s degree and recent experience: 3 years in the last 5 with a degree in tax, accounting or law (or another degree plus a recognised professional qualification), or 5 years in the last 8 with a degree in any other field. You also need good conduct, Arabic or English, professional indemnity insurance and a pass in the FTA’s qualifying tests.
How much does FTA tax agent registration cost?
AED 3,000 for every 3 years for a natural person and AED 10,000 for each year for a juridical person tax agent, under Cabinet Decision No. 65 of 2020 as amended (FTA copy dated 24 December 2025). Registering a tax agency is free according to the FTA service card.
Is there an exam to become a tax agent in the UAE?
Yes. The FTA schedules an Arabic exam and/or Qualification Standards Tests after you apply, and the service card asks for a VAT or corporate tax diploma. The FTA pages we read on 5 October 2026 do not publish the exam fee, format or pass mark.
How long does tax agent registration take?
The FTA service card gives 20 business days from a complete application. Under the regulation, our arithmetic gives 25 to 45 business days from a complete application to listing, excluding the time to sit the exam.
How do I renew my tax agent registration?
The FTA sends a notice 60 days before expiry and a Renewal button appears on EmaraTax. The regulation requires the request at least 20 business days before expiry; later requests count as a new application. A natural person renews for another 3 years.
How can a business check that a tax agent is registered?
The FTA publishes a searchable register of tax agents with filters by emirate and previous experience; it showed 858 entries on 5 October 2026. Each entry shows the agent’s TAAN number, firm and contact details.
Once you are listed, put your TAAN to work: list your firm and see what each lead costs on our pricing page.
Official references used for context in this article.
- Federal Tax Authority: Tax Agent Registration service card (page updated 19 August 2026)
- Federal Tax Authority: Registration of Tax Agency service card (page updated 19 August 2026)
- Federal Tax Authority: What requirements should I meet to be eligible to register as a Tax Agent (page updated 9 September 2025)
- Federal Tax Authority: Tax Agent Renewal (page updated 22 July 2025)
- Federal Tax Authority: Registered Tax Agents register (read 5 October 2026)
- Federal Tax Authority: UAE Tax Agent Programme (page updated 16 June 2026)
- Federal Tax Authority: FTA and New Economy Academy kick off training for inaugural Emirati Tax Agent Programme cohort (18 April 2026)
- Federal Decree-Law No. 28 of 2022 on Tax Procedures and amendments, FTA copy (3 December 2025)
- Cabinet Decision No. 74 of 2023 on the Executive Regulation of the Tax Procedures Law and amendments, FTA copy (1 April 2026)
- Cabinet Decision No. 65 of 2020 on FTA Services Fees and amendments, FTA copy (24 December 2025)
- Cabinet Decision No. 40 of 2017 on administrative penalties and amendments, FTA copy (November 2025)
- FTA Decision No. 14 of 2023 on additional conditions for a juridical person tax agent (16 August 2023)
- FTA Decision No. 15 of 2023 on CPD requirements for natural person tax agents (13 December 2023)
- Federal Tax Authority: Guidance on CPD for Natural Person Tax Agents (September 2025)
- Federal Tax Authority: Register Natural Person Tax Agent with Exam Schedule, user manual v1.2 (24 June 2024)
- Federal Tax Authority: Register Natural Person Tax Agent without Exam Schedule, user manual v1.2 (2024)

Need help with this?
Submit a request and receive tailored offers from verified UAE business consultants. Free, no obligation.